Archive
Info Inbox
info@turnpack.com
-
We Completed Your Policy Change Request
The Hartford
Don’t miss important emails! Add
businesscenter@mail.service.thehartford.com to your contacts.
info@turnpack.com Policy Number: 76WEGAX9Y65 See Updated Documents Online Dear Christopher, On September 16, 2026, a change was requested to a policy for TURNKEY PACKAGING SOLUTIONS. Your change is complete. You can see the updated policy document(s) online. TURNKEY PACKAGING SOLUTIONS Policy Number: 76WEGAX9Y65 Effective Date of Change: 09/16/2026 See What Changed Check out these other services next time you log in: • AutoPay – View your payment history, update payment information • Digital documents – See your bills and policy documents from the past two years • Profile preferences – Update your profile, manage account users On behalf of NUTMEG INS AGENCY INC/PHS, thanks for choosing us for your business insurance needs. Have a great day,
The HartfordPrivacy Policy Terms of Use Contact Us Update Preferences Update Email Address This email was sent to: info@turnpack.com This email was sent by: The Hartford.
3600 Wiseman Blvd. San Antonio, TX 78251, United States.© 2026 The Hartford. This is a customer service message from The Hartford. For security reasons, we kindly ask that you do not reply to this email. If you have questions regarding your account, please contact us or log in so we can properly verify your identity. For Arizona, California, New Hampshire, Texas and Washington, your (or the) specific insurance underwriting company can be easily obtained by viewing the insurance policy document accessed through the link as specified above.
von "The Hartford" <businesscenter@mail.service.thehartford.com> - 08:41 - 16 Sept. 2026 -
We Completed Your Policy Change Request
The Hartford
Don’t miss important emails! Add
businesscenter@mail.service.thehartford.com to your contacts. info@turnpack.com Policy Number: 76SBWAS7BC4 See Updated Documents Online Dear Christopher, On September 16, 2026, a change was requested to a policy for TURNKEY PACKAGING SOLUTIONS, LLC. Your change is complete. You can see the updated policy document(s) online. TURNKEY PACKAGING SOLUTIONS, LLC Policy Number: 76SBWAS7BC4 Effective Date of Change: 09/16/2026 See What Changed Check out these other services next time you log in: • AutoPay – View your payment history, update payment information • Digital documents – See your bills and policy documents from the past two years • Profile preferences – Update your profile, manage account users On behalf of NUTMEG INS AGENCY INC/PHS, thanks for choosing us for your business insurance needs. Have a great day,
The HartfordPrivacy Policy Terms of Use Contact Us Update Preferences Update Email Address This email was sent to: info@turnpack.com This email was sent by: The Hartford.
3600 Wiseman Blvd. San Antonio, TX 78251, United States.© 2026 The Hartford. This is a customer service message from The Hartford. For security reasons, we kindly ask that you do not reply to this email. If you have questions regarding your account, please contact us or log in so we can properly verify your identity. For Arizona, California, New Hampshire, Texas and Washington, your (or the) specific insurance underwriting company can be easily obtained by viewing the insurance policy document accessed through the link as specified above.
von "The Hartford" <businesscenter@mail.service.thehartford.com> - 08:41 - 16 Sept. 2026 -
Your Device Has Been Registered
The Hartford

Your Login Just Got Faster Dear Christopher, Thanks for registering your device. We’ll remember it from now on, so you won’t need to request a code again next time you use the same device to log in. If you didn’t save a device, please contact us. Thanks, The Hartford Privacy Policy Terms of Use Contact Us This email was sent to: info@turnpack.com This email was sent by: The Hartford One Hartford Plaza, Hartford, CT 06155 United States. © 2026 The Hartford. The Hartford® is The Hartford Insurance Group, Inc. and its subsidiaries, including underwriting companies Hartford Life and Accident Insurance Company and Hartford Fire Insurance Company. Home Office is Hartford, CT. This is a customer service message from The Hartford. For security reasons, we kindly ask that you do not reply to this email.
von "The Hartford" <myaccount@mail.service.thehartford.com> - 08:36 - 16 Sept. 2026 -
Your Insurance Audit Results Are Ready
The Hartford
To ensure delivery, add
businesscenter@mail.service.thehartford.com to your address book. info@turnpack.com Policy Number: 76WEGAX9Y65 View Your Audit Statement Online Dear Christopher, We’re writing to let you know that your audit is ready for review. You can see your Statement of Premium Adjustment online. TURNKEY PACKAGING SOLUTIONS Policy Number: 76WEGAX9Y65 Policy Period: 05/17/2025 - 05/17/2026 Policy Type: Workers' Compensation View Statement If you have questions about your statement or about audit in general, including frequently asked questions, visit us online. On behalf of the NUTMEG INS AGENCY INC/PHS, thank you for being a valued customer of The Hartford. This insurance was brought to you in partnership with Small Business. We appreciate your business! Sincerely,
The HartfordPrivacy Policy Terms of Use Contact Us Update My Profile Update Email Address This email was sent to: info@turnpack.com This email was sent by: The Hartford.
3600 Wiseman Blvd. San Antonio, TX 78251, United States.© 2026 The Hartford. This is a customer service message from The Hartford. For security reasons, we kindly ask that you do not reply to this email. If you have questions regarding your account, please contact us or log in so we can properly verify your identity. For Arizona, California, New Hampshire, Texas and Washington, your (or the) specific insurance underwriting company can be easily obtained by viewing the insurance policy document accessed through the link as specified above.
von "The Hartford" <businesscenter@mail.service.thehartford.com> - 08:32 - 16 Sept. 2026 -
FedEx Billing Online Payment Reference 59542289

FedEx payment scheduled. Log in to review. 

Payment Scheduled Dear christopher berger, An automatic payment has been scheduled for your FedEx account number ending in 6805 using payment profile TURNPACK PLATINUM.Log in to FedEx® Billing Online to review the invoices included in this payment. Invoice Number Amount 9-465-23615 17.03 USD 9-465-23614 100.40 USD Log in Thank you for your business, FedEx ©2026 FedEx. The content of this message is protected by copyright and trademark laws under U.S. and international law.
Review our privacy policy. All rights reserved.
This message has been sent by an auto responder system. Please do not reply to this message.
von "BillingOnline" <BillingOnline@fedex.com> - 08:12 - 16 Sept. 2026 -
[Preview] Report Domain: turnpack.com Submitter: enterprise.protection.outlook.com Report-ID: f294c46b3d094840b3192d3cc0c6c6e4
This is a DMARC aggregate report from Microsoft Corporation. For Emails received between 2026-09-14 00:00:00 UTC to 2026-09-15 00:00:00 UTC. div>
You're receiving this email because you have included your email address in the 'rua' tag of your DMARC record in DNS for turnpack.com. Please remove your email address from the 'rua' tag if you don't want to receive this email.Please do not respond to this e-mail. This mailbox is not monitored and you will not receive a response. For any feedback/suggestions, kindly mail to dmarcreportfeedback@microsoft.com.
Microsoft respects your privacy. Review our Online Services Privacy Statement.
One Microsoft Way, Redmond, WA, USA 98052. div >
von "DMARC Aggregate Report" <dmarcreport@microsoft.com> - 05:02 - 16 Sept. 2026 -
SMC Formal Invoice #: SMC- 340917
SMCpneumatics.com

Phone: 800.660.0733
sales@ocaire.comFormal Invoice
Christopher Berger,
This email confirms that your order was received at SMCpneumatics.com. You will receive an additional email once your order is shipped. Contact us if you have any questions about your order.
Thanks for using SMCpneumatics.com.Order Information Additional Information Order number: SMC-340917
Order Date: 9/15/2026
Account Info:
Login: info@turnpack.com
Pass: ******Billing Address Payment Information Christopher Berger
Turnpack
info@turnpack.com
4803311878
6922 E Via Northgate Ste 101
101
Mesa, AZ 85212-1296 USPayment Method
Online Credit CardOrder Summary Shipping To: Christopher Berger Turnpack
6922 E Via Northgate Ste 101 101 Mesa, AZ 85212-1296 USShipping Method
UPS - Ground
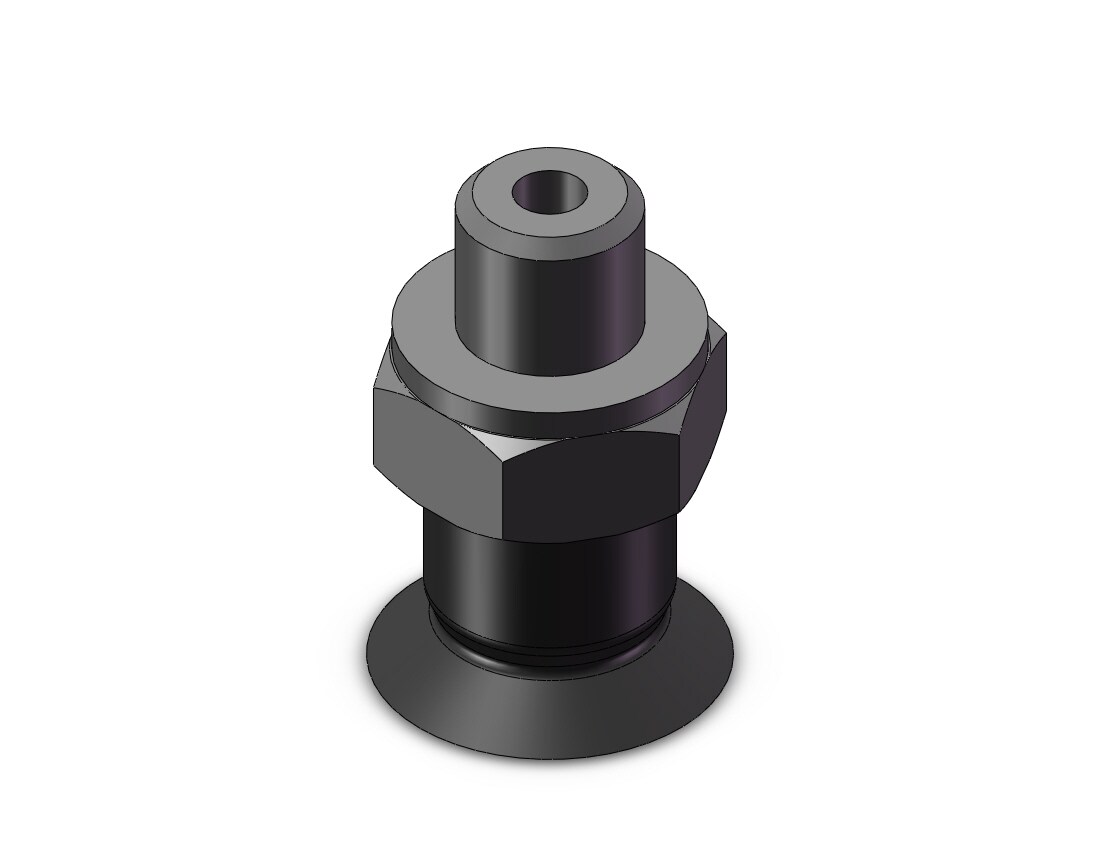
ZP2-TB05MUGN-A3 SMC ZP2-TB05MUGN-A3 short type pad w/adapter, OTHER OTHER MISC.***
Available to Ship in 7 Days: 83 qty$11.10 x 20$222.00
*If stock is 0, please estimate 4 to 6 weeks for delivery.
All in-stock orders ship the next business day if received before 3pm PST unless otherwise specified. We ship Monday through Friday only.
International orders add 5 days for handling.Subtotal: $222.00
Discount: $0.00
Shipping/Processing: $24.28
Tax: $0.00
Total: $246.28Checkout Questions Purchase Order Number: PO26341899
My Shipping Carrier and Account # (only available for orders over $100. Required for ALL International orders.):
Residential Address:
Partial Shipment OK:
Order History- SMC-331562 6/12/2026
- SMC-323671 3/19/2026
- SMC-327458 4/30/2026
- SMC-322193 3/4/2026
- SMC-318135 1/21/2026
- SMC-314464 12/4/2025
- SMC-314464 12/4/2025
- SMC-313445 11/20/2025
- SMC-310116 10/16/2025
- SMC-308093 9/25/2025
SMCpneumatics.com 3810 Prospect Ave., Unit A Yorba Linda, CA 92886
Phone: 800.660.0733
von sales@ocaire.com - 12:36 - 16 Sept. 2026 -
THK account email verification code
THK account email verification code
Verify your email address
Thanks for verifying your info@turnpack.com account!
Your code is: 362564
Sincerely,THK
von "Microsoft on behalf of THK" <msonlineservicesteam@microsoftonline.com> - 10:02 - 15 Sept. 2026 -
Thank you for your order with MISUMI NB11458B42 (Your PO: PO26361912) (000Y7G)
Thank you for your order with MISUMI NB11458B42 (Your PO: PO26361912) (000Y7G)

THANK YOU Hi Chris Berger, Thank you for your order. Please find our Sales Order Confirmation details below for your review. Your PO: PO26361912 MISUMI Order No.: NB11458B42 Order Date: 09/15/2026 8:17 PM ORDER USER: Department: Name: Chris Berger INVOICE: Customer Code: 000Y7G Company Name: Turnpack, LLC Department: Address: 6922 VIA NORTHGATE ST STE 101 MESA, AZ 85212 USA Attention: Chris Berger SHIPPING ADDRESS: Address: 6922 E Via Northgate 101 Mesa, AZ 85212 USA Department: Attention: Shipping TEL: 4803311878 SHIPPING DETAILS: Ship Via(Service): UPS Ground Prepaid Payment: Sales on Credit Carrier Account No.: ITEMS PURCHASED: Line No.: 1 Status: Completed Customer Item Reference: MISUMI Part No: LVWS16-15 Brand Name: MISUMI Product Name: SCREW STOPPER Quantity: 2 Unit Price: 9.81(USD) Available/Shipping Date: 09/18/2026 Express: Amount: 19.62(USD) Product Total: 19.62(USD) Product Discount: 0(USD) Shipping Charges: 15.62(USD) Total Weight: 30(g) Tax: 0(USD) TOTAL: 35.24(USD) View Your Order History Our staff will contact you as soon as possible about any item "On Hold". This order is subject to MISUMI's current cancellation policy. Pick up Orders at the following locations and times: OHIO: 400 Progress Road, West Carrollton OH 45449 ILLINOIS: 2400 Lunt Avenue, Elk Grove Village IL 60007 CALIFORNIA: 19701 Magellan Drive, Torrance CA 90502 Many orders are available for pick-up the same day. Orders before 2:00PM may be available as early as 3:00PM (local time). Please call Customer Service at 800.681.7475 to confirm availability. Thank you! MISUMI Customer Service MISUMI inquire@misumiusa.com | 800.681.7475 1475 E Woodfield Rd, Ste. 1300 | Schaumburg, IL 60173 


** This e-mail message was sent to you by an automated e-mail system **
von "MISUMI USA Customer Service" <inquire@misumiusa.com> - 09:21 - 15 Sept. 2026 -
Payment Needed for the Balance Due on PO PO26261824 with McMaster-Carr
Hi Lorena,
Please assist us with payment of $47.15 for the balance due on PO PO26261824 (invoice 67607756).
We issued credit 68361893 for the return of lines 1 and 5, which you applied to invoice 67607756 on August 10th, leaving a balance of $47.15 due.
May we apply your Amex ending in -1004 to resolve the balance of your June invoice? Otherwise, you may return to your Order History page to apply payment online.
I attached your invoice to review.
Kathy
From: info@turnpack.com
Sent: Monday, August 10, 2026 11:42 PM
To: la.sales@mcmaster.com
Subject: Re: Please Send Payment for your Past Due BalancePlease apply credit to invoice
67607756 and 68361893
Other invoices have been paid
Respectfully,
Lorena CarrilloOn Mon, Aug 10, 2026, 9:36?PM McMaster-Carr <la.sales@mcmaster.com> wrote:
Please send payment for your past due balance with McMaster-Carr. A Statement of Account is attached.
von "McMaster-Carr" <la.sales@mcmaster.com> - 08:16 - 15 Sept. 2026 -
September 2026 - Transaction Privilege Tax Changes and News
September 2026 - Transaction Privilege Tax Changes and News
ADOR is preparing for the upcoming 2027 TPT License renewal period. Renewal notices will be sent to businesses to renew their license by January 1.͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ 
TPT Newsletter
September 2026
Transaction Privilege Tax Changes and News
TPT Renewal Season is Upon Us
Overview & Schedule
The Arizona Department of Revenue (ADOR) is preparing for the upcoming 2027 Transaction Privilege Tax (TPT) License renewal period. Renewal notices will be sent to businesses to renew their license by January 1. The option to electronically renew your license will be available soon.ADOR advises taxpayers to register on AZTaxes.gov today to ensure streamlined processing and a faster renewal experience.
Notification Methods by Filer Type
Paper Filers: A physical Renewal Form will be sent by mail.
E-Filers: Notifications by email, mail, and/or direct reminders posted on AZTaxes.gov. Taxpayers enrolled on AZTaxes.gov should verify and update their account details prior to renewing to avoid unexpected fees or penalties.
Account Maintenance & Cancelations
If a business is fully closed, its TPT license must be formally canceled. For companies operating multiple locations where one or more sites have shut down, those specific closed locations must be removed from the license. Unrenewed licenses will not be canceled automatically; instead, they will auto-renew and incur applicable fees and penalties.
Special Requirements
Multiple Business Locations: Under state law, taxpayers with more than one location must process their TPT license renewals electronically.
Out-of-State Businesses: Remote businesses without a physical presence in Arizona must renew their TPT license if their sales to Arizona customers exceed $100,000 during the current calendar year.
Marijuana Licenses: Marijuana TPT licenses require annual renewal, but marijuana excise tax licenses do not.
New Town of San Tan Valley TPT Effective October 1, 2026
The Town of San Tan Valley was officially incorporated on September 17, 2025. Effective October 1, 2026, the Town will begin imposing a local TPT in the same manner as other Arizona cities and towns. Businesses located within the Town boundaries that currently pass the economic burden of the TPT on to their customers will need to reprogram their point-of-sale systems to include the Town’s tax. All businesses within the Town boundaries will need to include the Town’s tax in their TPT returns and payments for periods beginning from and after October 1, 2026.
The new city code is SZ.
As of October 1, 2026, business codes associated with the new city code can be found in the AZ Tax Rate Look Up at AZTaxes.gov/Home/Address.
See the Town’s profile page for more information on its tax rates: https://azdor.gov/model-city-tax-code/city-profile/san-tan-valley.
Businesses within the Town’s boundaries will be mailed updated TPT licenses.
Construction contracts in effect before October 1, 2026 may qualify for pre-existing contract treatment–check with the Town directly for more information.
ADOR Customer Care Call Center Saturday HoursThe Customer Care Call Center is available to assist taxpayers Monday through Friday from 7 a.m. to 6 p.m. and on the second and fourth Saturday of each month from 8 a.m. to noon, except on state holidays.
Taxpayers with questions can contact the Customer Care Call Center at (602) 255-3381 or toll-free: 800-352-4090.
Note: These Saturday hours apply to our general Call Center support and do not include the Collections department.
TPT Account Updates
Did you close a location or change the mailing address of your business?
Renewal season is coming and you should submit any necessary updates before October to ensure your account is in good standing for a smooth renewal process.
On AZTaxes.gov, taxpayers can do the following:
Change their mailing address on corporate, withholding, and transaction privilege and use tax licenses.
Add, edit, and/or close locations for TPT licenses.
Cancel or close an existing TPT license or single location on a TPT license.
Add a new reporting jurisdiction, business code, or business or rental location.
AZTaxes.gov enables registered businesses to update their accounts, but they must have an e-signature PIN to make changes.
Taxpayers can also download and submit a Business Account Update Form to ADOR to update primary users or any of the previously stated changes.
ACH Debit Payment Banking Transition
ADOR has transitioned Automated Clearing House (ACH) Debit payment banking services to JP Morgan Chase. All ACH Debit customers need to contact their bank to provide the new Company ID: 9031897000 to ensure that ACH debit transactions process as expected.
File Online for Quicker Processing
When taxpayers file electronically, they receive many benefits and are in compliance.
It’s EASIER, it’s FASTER, and it’s THE LAW for businesses with $500 or more annual tax liability.
It is free to file a return; free for e-check payments (Fees apply with debit/credit card).
TPT filers are able to claim an accounting credit of 1.2 percent of the tax due, up to a maximum credit of $12,000, during a calendar year when filing all returns electronically.
After a payment or return is submitted, filers receive a confirmation number that can be provided to customer service when inquiring about the return or payment.
Reduced errors with automatic calculations. Input the figures and AZTaxes does the rest.
Access to electronic payment history and status as early as your first payment.
Make scheduled payments online so the return is done and the payment is withdrawn later. No need for paper checks.
If you are unable to pay online, follow these simple steps to ensure your payment is applied to your account.
Address the payment to the Arizona Department of Revenue.
In the memo, write your license number and filing period.
Submit your paper check with the original return or a payment voucher. If you filed electronically, send a voucher, not a copy of the return.
Note: ADOR will process your check and withdraw the money from your bank account even if you do not properly indicate your business information. ADOR will research and attempt to connect the payment to the business. If not successful, the payment will be held in a general fund account until it is properly identified for your business and the time period. ADOR legally cannot mail the check back in case of incorrect address on check and prevent fraud.
Primary User and Delegate Access Update Guidance
Did your primary user leave the company or did you deactivate the email address that is used to log into AZTaxes? No problem. The Arizona Department of Revenue recommends that the primary user is an officer/owner of the business, then delegate access to others if needed. This reduces the chance of losing access to your account and rushing to update information before the due date.
A Primary User maintains the entire online account and provides access to delegate users. There can only be one Primary User for each account. View our tutorial for help authorizing access for delegates.
A Delegate User is given specific authority for business account functions by the Primary User. This type of user can be a CPA, paid preparer, office manager, additional officer/owner of the company, etc. View our tutorial for help requesting delegate access.
To change the Primary User, you will need to complete a Business Account Update Form; and you must enroll to file and pay on AZTaxes.gov with the new email address. NOTE: DO NOT use the Business Account Update Form for delegates/additional users. Please contact the primary user for changes to delegate access.
The company will need to register as a new user. See Account Setup for assistance.
Once registered, you will need to complete a paper Business Account Update to change the primary user to the new user account.
Section A, line 4 is for adding and removing AZTaxes Primary Users.
Have Section C signed by an authorized officer/owner and submit to the address on the form.
Once the primary is switched to an office/owner, they can grant delegate access to other registered users.
Due Date Reminders
TPT Filing Frequency and Due Dates*- Monthly
If you’re a TPT filer, keep the following August TPT filing deadlines in mind:
September 21 - TPT return due date.
September 29 - Paper returns must be received at ADOR by this date.
September 30 - Electronic return filed in AZTaxes must be submitted before 11:59 p.m. on this date. Electronic payment made in AZTaxes must be submitted before 11:59 p.m. on this date.
*The electronic due date for TPT return is dependent on the return and payment being timely and filed electronically.
Tax Changes
Town of Huachuca City - Effective Date of August 1, 2026
On May 28, 2026, the Mayor and Council of the Town of Huachuca City passed Ordinance No. 2026-06 providing an increased tax rate on multiple Privilege Tax business classifications and Use Tax from one and nine-tenths percent (1.9%) to two and nine-tenths percent (2.9%), and Rental, Leasing and Licensing for Use of Real Property from one percent (1%) to two and nine-tenths percent (2.9%). Providing for Severability.The (2.9%) affects the following business classifications:
Advertising (018); Amusement (012); Contracting-Prime (015); Contracting-Speculative Builders (016); Feed at Wholesale (116); Job Printing (010); Manufactured Buildings (027); Timbering and other Extractions (020); Publication (009); Hotels (044); Commercial, Rental, Leasing, and Licensing for Use (213); Rental, Leasing, and Licensing for Use of TPP (214); Restaurant and Bars (011); Retail Sales (017); MRRA Amount (315); Communications (005); Transporting (006); Utilities (004); Use Tax Purchases (029); Use Tax from Inventory (030).Medical and Adult Use Marijuana:
Medical Marijuana Retail Sales (203); Adult Use Marijuana Retail Sales (420); Retail Sales (Accessories and Ancillary Products) (017); Use Tax Purchases (029); Use Tax From Inventory (030); Medical Marijuana Restaurant (221); Adult Use Marijuana Restaurant (421).Remote Seller and Marketplace Facilitators:
Retail Sales (605); Marketplace Facilitators in Arizona Retail Sales (017); Marketplace Facilitators in Arizona Third Party Sales (605).City of Kingman - Effective Date of September 1, 2026
On June 16, 2026, the Mayor and Council of the City of Kingman passed Ordinance No. 2003 providing an increased tax rate on multiple Privilege Tax business classifications and Use Tax from two and one-half percent (2.50%) to three percent (3.00%), and Rental, Leasing and Licensing for Use of Real Property from two percent (2.00%) to three percent (3.00%), and Additional Tax on Transient Lodging from four percent (4.00%) to five percent (5.00%), and Adopting Local Option V, for single item transactions exceeding the ten thousand dollars ($10,000) threshold, the entire single item will be taxed at a rate of two and one-half percent (2.5%). Providing for Severability.The (3.00%) affects the following business classifications:
Advertising (018); Amusement (012); Contracting-Prime (015); Contracting-Speculative Builders (016); Contracting-Owner Builder (037); Job Printing (010); Manufactured Buildings (027); Timbering and other Extractions (020); Publication (009); Hotels (044); Commercial, Rental, Leasing, and Licensing for Use (213); Rental, Leasing, and Licensing for Use of TPP (214); Restaurant and Bars (011); Retail Sales (017); MRRA Amount (315); Communications (005); Transporting (006); Utilities (004); Use Tax Purchases (029); Use Tax from Inventory (030).Medical and Adult Use Marijuana:
Medical Marijuana Retail Sales (203); Adult Use Marijuana Retail Sales (420); Retail Sales (Accessories and Ancillary Products) (017); Use Tax Purchases (029); Use Tax From Inventory (030); Medical Marijuana Restaurant (221); Adult Use Marijuana Restaurant (421).
Remote Seller and Marketplace Facilitators:
Retail Sales (605); Marketplace Facilitators in Arizona Retail Sales (017); Marketplace Facilitators in Arizona Third Party Sales (605).
The (5.00%) affects the following business classifications:
Hotel/Motel (Additional Tax) (144).
The (2.50%) affects the following business classifications:
Retail Sales (Single Item Over $10,000) (917); Use Tax Purchases (Single Item Over $10,000) (929).
Medical and Adult Use Marijuana:
Medical Marijuana Retail Sales-Single Item Over $10,000 (665); Adult Use Marijuana Retail Sales-Single Item Over $10,000 (681); Retail Sales (Accessories and Ancillary Products)-Single Item Over $10,000 (917); Use Tax Purchases-Single Item Over $10,000 (929).
Remote Seller and Marketplace Facilitators:
Retail Sales-Single Item Over $10,000 (624); Marketplace Facilitators in Arizona Retail Sales-Single Item Over $10,000 (917); Marketplace Facilitators in Arizona Third Party Sales-Single Item Over $10,000 (624).
Town of Tusayan - Effective Date of October 1, 2026
On July 14, 2026, the Mayor and Council of the Town of Tusayan passed ordinance 2026-02 providing an increased tax rate on multiple Privilege Tax business classifications from two percent (2%) to four percent (4%) and an increased rate on Restaurants and Bars from four percent (4%) to six percent (6%). Providing for SeverabilityThe (4.00%) affects the following business classifications:
Advertising (018); Amusement (012); Contracting-Prime (015); Contracting-Speculative Builders (016); Contracting-Owner Builder (037); Job Printing (010); Manufactured Buildings (027); Timbering and other Extraction (020); Publication (009); Hotels (044); Commercial, Rental, Leasing, and Licensing for Use (213); Rental, Leasing, and Licensing for Use of TPP (214); Retail Sales (017); Communications (005); Transporting (006); Utilities (004).Medical and Adult Use Marijuana:
Medical Marijuana Retail Sales (203); Adult Use Marijuana Retail Sales (420); Retail Sales (Accessories and Ancillary Products) (017).Remote Seller and Marketplace Facilitators:
Retail Sales (605); Marketplace Facilitators in Arizona Retail Sales (017); Marketplace Facilitators in Arizona Third Party Sales (605).The (6.00%) affects the following business classifications:
Restaurant and Bars (011).Medical and Adult Use Marijuana:
Medical Marijuana Restaurant (221); Adult Use Marijuana Restaurant (421).Town of San Tan Valley - Effective Date of October 1, 2026 and January 1, 2027 The newly incorporated Town of San Tan Valley passed on July 1, 2026 Ordinance No. 2026-06 and Resolution No. 2026-41, adopting the Model City Tax Code and selected options.
Providing for Severability; and designating an effective date of October 1,2026 for:
The imposition of the Transaction Privilege and Use Tax License Fee of two dollars ($2.00) and License Renewal Fee of two dollars ($2.00).
The imposition of multiple Privilege Tax business classifications and Use Tax at two and one-quarter percent (2.25%); Hotels and Hotel/Motel (Additional Tax) at four and one-quarter percent (4.25%); all construction contracting at fi ve percent (5.00%) and Metal Mining at one-tenth of one percent (0.10%).
The adoption of the following options:Local Option H
Amusements, to impose tax on membership fees/charges for use.
Local Option P
Feed at Wholesale, to impose tax on sales of wholesale feed and related products.
Local Option GG
Utilities, to impose tax on municipal utilities provided to residents outside of Town Limits.
Local Option JJ
Use Tax, to exempt purchases made by the city from Use Tax.
Model Option 3
Job Printing, to impose tax on job printing sold to publishers.
Model Option 4
Rental, Leasing and Licensing for Use of Real Property, to impose tax on the rental of real property to nonprofit primary health care facilities.
Model Option 7
Rental, Leasing, and Licensing for Use of Tangible Personal Property, to impose tax on the rental of coin-operated machines.
Model Option 11
Communications, to disallow tax credit for franchise and license fees paid to the municipality.
Model Option 12
Transporting for Hire, to exempt transporting persons for hire.
Model Option 13
Utilities, to disallow tax credit for franchise fees paid to the municipality.
In the same Ordinance No. 2026-06, providing for Severability; and designating an effective date of January 1, 2027, the Mayor and Council of the Town of San Tan Valley passed the imposition of Retail Sales Food for Home Consumption at two and one-quarter percent (2.25%).
The (2.25%) affects the following business classifi cations: Advertising (018); Amusements (012); Feed at Wholesale (015); Job Printing (010); Manufactured Buildings (027); Timbering and other Extraction (020); Publication (009); Rental, Leasing, and Licensing for Use of TPP (214); Commercial Rental, Leasing, and Licensing for Use (213); Restaurant and Bars (011); Retail Sales (017); Retail Sales Food for Home Consumption effective January 1, 2027 (062); MRRA Amount (315); Communications (005); Transporting (006); Utilities (004); Use Tax Purchases (029).
Medical and Adult Use Marijuana: Medical Marijuana Retail Sales (203); Adult Use Marijuana Retail Sales (420); Retail Sales (Accessories and Ancillary Products) (017); Medical Marijuana Restaurant (221); Adult Use Marijuana Restaurant (421); Use Tax Purchase (029).
Remote Seller and Marketplace Facilitators: Retail Sales (605); Marketplace Facilitators in Arizona Retail Sales (017); Marketplace Facilitators in Arizona Third Party Sales (605); Retail Sales Food for Home Consumption effective January 1, 2027 (606); Marketplace Facilitators in Arizona Retail Sales Food for Home Consumption effective January 1, 2027 (062); Marketplace Facilitators in Arizona Third Party Sales Food for Home Consumption effective January 1, 2027 (606).
The (5.00%) affects the following business classifications: Contracting - Prime (015); Contracting - Speculative Builders (016); Contracting - Owner Builder (037).
The (0.10%) affects the following business classifications: Severance - Metal Mining (019).
The (4.25%) affects the following business classifications: Hotels (044); Hotel/Motel (Additional Tax) (144).
Education, Tutorials and Training
All ADOR workshops are free of charge. Below are upcoming options available to you. To register or access online workshops, tutorials and resources, visit azdor.gov/taxpayer-education.
WORKSHOPS
ADOR Business Tax Basics - (Via Google Meets)
Wednesday, September 16, 2026
1:00 p.m. – 4:00 p.m.Tuesday, October 6, 2026
9:00 a.m. – noonADOR Common TPT Errors and How to Avoid Them - (Via Google Meets)
Thursday, September 17, 2026
1:00 p.m. – 2:00 p.m.
Wednesday, October 7, 2026
10:00 a.m. – 11:00 a.m.ADOR Withholding Tax for Employers and Payroll Service Providers - (Via Google Meets)
Tuesday, September 29, 2026
9:00 a.m. – noonON-DEMAND TAX EDUCATION TUTORIALS: Please visit https://azdor.gov/taxpayer-education/tpt-tutorials


Copyright (C) 2026 Arizona Department of Revenue. All rights reserved.
You are receiving this email because you opted in via our website.
Contact Us
Want to change how you receive these emails?You can update your preferences or unsubscribe
von "Arizona Department of Revenue" <MassEmail@azdor.gov> - 08:01 - 15 Sept. 2026 -
Precision parts for — quote from your drawing in 24h
Hi,
I'm Frank with Hongfeng Precision (Dongguan, China). We machine custom parts for automation and machinery OEMs 5-axis CNC machining, CNC turning, injection molding and die casting under one roof, about 500 CNC machines, certified to ISO 9001, ISO 13485 and IATF 16949.
Most of our customers use us as overflow or second-source capacity next to their existing shops.
If you send over one drawing (STEP or PDF), we'll return a firm quote with DFM feedback within 24 hours. NDA-friendly happy to sign yours first.
Would it make sense to send a part you're currently sourcing?
Best regards,
Frank
Hongfeng Precision · Dongguan, China
If you no longer wish to receive these emails you may unsubscribe
von "Thomas Nie" <sales@hfcncmach.com> - 07:47 - 15 Sept. 2026 -
Second Chance Picks + Trending Items for You, Friend
🧠 We Picked These Just for You FriendFresh picks based on your past bids and browsing. Jump back in there → Log In to My Account 
Auction My Account Help Desk 
ITEMS WON 0 SAVINGS VS RETAIL $ AVERAGE % OFF 0% 

No-Hassle Returns:
If it’s not right, return it within 7 days for a full refund.
No penalties, no stress.Need help? Visit our Help Desk anytime. 


Auction My Account Help Desk Watn to change how you receive these emails? You can Update Your Preferences or Unsubscribe © Copyright 2025 nellisauction.com. All Rights Reserved. 
von "Nellis Auction" <nelli@nellisauction.com> - 07:26 - 15 Sept. 2026 -
We have your shipment 877201735580.
FedEx
We have an estimated delivery date for your shipment.
We have your shipment. Your package is at our facility. We'll let you know when it moves again.
Scheduled delivery date Mon, 09/21/2026
Before 5:00pm
Take more control of your shipments MANAGE DELIVERY Some delivery options might not be available on the day of delivery. Personal message Avis Damage dispute 2690419360 U662727391 Tracking details Tracking ID 877201735580 From Turnpack LLC
christopher berger
6922 East Via Northgate
Suite 101
Mesa, AZ, US
85212To Avis Budget Group, Inc
6 SYLVAN WAY
PARSIPPANY, NJ, US
07054Ship date Tue 9/15/2026 03:28 PM Number of pieces 1 Total shipment weight 0.50 LB Service FedEx Economy Reference Avis Shipper reference Avis Department number U662727391 Purchase order number 2690419360 TRACK SHIPMENT 
Combine your shopping and shipping Out and about? Drop off or pick up your packages at nearby retail locations, including FedEx Office, Walgreens, Dollar General, and many more. Some are even open 24 hours. FIND LOCATIONS This tracking update has been requested by: Company name christopher berger Name Turnpack LLC Email info@turnpack.com
 Please do not reply to this message. This email was sent from an unattended mailbox.
All weights are estimated.
© 2026 FedEx. All rights reserved.
Scammers can pose as legitimate organizations to seem convincing. We encourage you to stay cautious of unknown messages – delete them and visit the FedEx Fraud & Security page to help keep your information safe.
Thank you for your business.
ID 1029Terms of Use Privacy notice Support Fraud & security
von "FedEx Tracking" <TrackingUpdates@fedex.com> - 06:41 - 15 Sept. 2026 -
Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717
Dear Customer,
After applying all open credits to your open invoices, you are due for $2,622.60.
Please let us know when we can expect that pmt.
Thank you and best regards,
Jeff Steele
Manager, Credit & Collections
AMADA WELD TECH INC.
1820 S. Myrtle Ave.
Monrovia, CA 91016 USA
Office: 626-930-8594
FAX: 626-358-4768
E-Mail: jeff.steele@amadaweldtech.com
This e-mail is intended solely for the person or entity to which it is addressed and may contain confidential and/or privileged information. Any review, dissemination, copying, printing or other use of this e-mail by persons or entities other than the addressee is prohibited. If you have received this e-mail in error, please contact the sender immediately and delete the material from any computer.
von Jeff Steele - 05:46 - 15 Sept. 2026-
RE: Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717
You are correct. This is an unusual situation. You were in a credit balance until July, when the last invoice came due. Without the open credits, you would have been contacted much sooner.
I will watch the account myself. If I see anything dragging out too long, I will contact you directly. We appreciate your efforts and want to make it as easy as possible on you.
Thank you for your patience and understanding.
Jeff Steele
Manager, Credit & Collections
AMADA WELD TECH INC.
1820 S. Myrtle Ave.
Monrovia, CA 91016 USA
Office: 626-930-8594
FAX: 626-358-4768
E-Mail: jeff.steele@amadaweldtech.com
This e-mail is intended solely for the person or entity to which it is addressed and may contain confidential and/or privileged information. Any review, dissemination, copying, printing or other use of this e-mail by persons or entities other than the addressee is prohibited. If you have received this e-mail in error, please contact the sender immediately and delete the material from any computer.
From: Turnpack LLC <info@turnpack.com>
Sent: Wednesday, September 23, 2026 1:37 PM
To: Jeff Steele <Jeff.Steele@AmadaWeldTech.com>
Cc: 'Christopher Berger' <cberger@turnpack.com>; 'Samantha Roman' <sroman@turnpack.com>
Subject: RE: Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717Understood. We had no problem paying this invoice once we received the new parts since the original order was damaged. I of course did not enter the invoice in our system as the parts were returned. It was just an oversight on my part when the r
External sender <info@turnpack.com>
Make sure you trust this sender before taking any actions.Understood. We had no problem paying this invoice once we received the new parts since the original order was damaged. I of course did not enter the invoice in our system as the parts were returned. It was just an oversight on my part when the replacement parts came in in and I apologize.
Totally easy to manage at this site I do deal with quite a lot so oversights can happen, and I wouldn’t want that to affect our account. Since its now September and I wasn’t aware of the issue until now. Just trying to find a way for us to all stay on the same page if any issues arise. Thanks!
Thank you for your time,
Lorena Carrillo
From: Jeff Steele <Jeff.Steele@AmadaWeldTech.com>
Sent: Wednesday, September 23, 2026 1:22 PM
To: Turnpack LLC <info@turnpack.com>
Cc: 'Christopher Berger' <cberger@turnpack.com>; 'Samantha Roman' <sroman@turnpack.com>
Subject: RE: Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717Hello Lorena,
Thank you for your quick reply.
We do not routinely send monthly statements. You are welcome to request a statement at any time and we usually respond within 2 business days. If you receive an invoice that you cannot pay timely, you can reach out to me anytime.
Your company only averages about 3 to 5 invoices per year with us. Hopefully, we should easily manage this volume going forward.
Thank you again and best regards,
Jeff Steele
Manager, Credit & Collections
AMADA WELD TECH INC.
1820 S. Myrtle Ave.
Monrovia, CA 91016 USA
Office: 626-930-8594
FAX: 626-358-4768
E-Mail: jeff.steele@amadaweldtech.com
This e-mail is intended solely for the person or entity to which it is addressed and may contain confidential and/or privileged information. Any review, dissemination, copying, printing or other use of this e-mail by persons or entities other than the addressee is prohibited. If you have received this e-mail in error, please contact the sender immediately and delete the material from any computer.
From: Turnpack LLC <info@turnpack.com>
Sent: Wednesday, September 23, 2026 1:10 PM
To: Jeff Steele <Jeff.Steele@AmadaWeldTech.com>
Cc: 'Christopher Berger' <cberger@turnpack.com>; 'Samantha Roman' <sroman@turnpack.com>
Subject: RE: Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717Hello Jeff I found the discrepancy regarding damaged parts we had sent back. I have updated our system and Chris will pay shortly. For future reference and get ahead of issues like this, is it possible to email monthly statements so I can ensure our sy
External sender <info@turnpack.com>
Make sure you trust this sender before taking any actions.Hello Jeff I found the discrepancy regarding damaged parts we had sent back. I have updated our system and Chris will pay shortly.
For future reference and get ahead of issues like this, is it possible to email monthly statements so I can ensure our systems align?
Thank you for your time,
Lorena Carrillo
From: Turnpack LLC <info@turnpack.com>
Sent: Wednesday, September 23, 2026 12:40 PM
To: 'Jeff Steele' <Jeff.Steele@AmadaWeldTech.com>
Cc: 'Christopher Berger' <cberger@turnpack.com>; 'Samantha Roman' <sroman@turnpack.com>
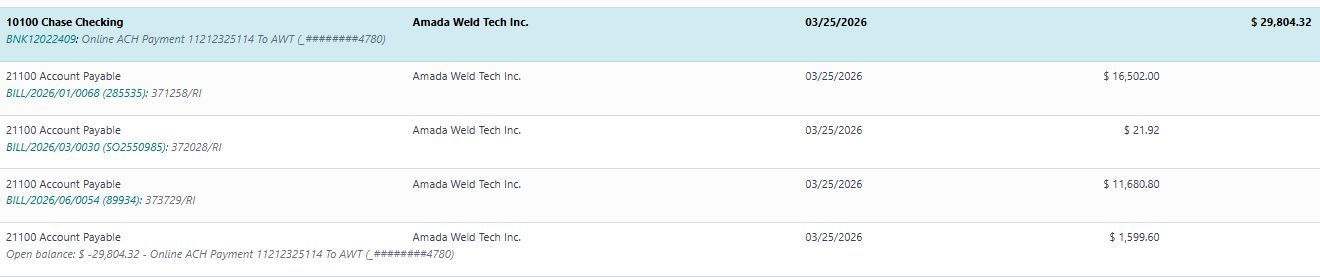
Subject: RE: Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717Thank you for the details I will look into this but again 373729 for $11,680.80 was paid, see below, so not sure why its on the report.
Thank you for your time,
Lorena Carrillo
From: Jeff Steele <Jeff.Steele@AmadaWeldTech.com>
Sent: Monday, September 21, 2026 3:05 PM
To: Turnpack LLC <info@turnpack.com>
Subject: RE: Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717Hi Lorena,
You were issued 2 credit memos. See attached.
Thank you,
Jeff Steele
Manager, Credit & Collections
AMADA WELD TECH INC.
1820 S. Myrtle Ave.
Monrovia, CA 91016 USA
Office: 626-930-8594
FAX: 626-358-4768
E-Mail: jeff.steele@amadaweldtech.com
This e-mail is intended solely for the person or entity to which it is addressed and may contain confidential and/or privileged information. Any review, dissemination, copying, printing or other use of this e-mail by persons or entities other than the addressee is prohibited. If you have received this e-mail in error, please contact the sender immediately and delete the material from any computer.
From: Turnpack LLC <info@turnpack.com>
Sent: Thursday, September 17, 2026 12:53 PM
To: Jeff Steele <Jeff.Steele@AmadaWeldTech.com>
Subject: FW: Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717Hey sorry I should have looked at this better 373729/RI was paid 3/25 372028/RI 69T3008 $6640.20 was returned (373158 \ RM) 1NT7019 $4222.20 was returned We paid the $21.92 shipping Is there any other paperwork missing? Thank you for you
Warning: Unusual sender <info@turnpack.com>
You don't usually receive emails from this address. Make sure you trust this sender before taking any actions.Hey sorry I should have looked at this better
373729/RI was paid 3/25
372028/RI
69T3008 $6640.20 was returned (373158 \ RM)
1NT7019 $4222.20 was returned
We paid the $21.92 shipping
Is there any other paperwork missing?
Thank you for your time,
Lorena Carrillo
From: Jeff Steele <Jeff.Steele@AmadaWeldTech.com>
Sent: Tuesday, September 15, 2026 2:44 PM
To: ap@turnpack.com
Subject: Turnpack Inv 372028/RI and 373729/RI, CM 373158/RM and 374344/RM due Amada / CN 320717Dear Customer,
After applying all open credits to your open invoices, you are due for $2,622.60.
Please let us know when we can expect that pmt.
Thank you and best regards,
Jeff Steele
Manager, Credit & Collections
AMADA WELD TECH INC.
1820 S. Myrtle Ave.
Monrovia, CA 91016 USA
Office: 626-930-8594
FAX: 626-358-4768
E-Mail: jeff.steele@amadaweldtech.com
This e-mail is intended solely for the person or entity to which it is addressed and may contain confidential and/or privileged information. Any review, dissemination, copying, printing or other use of this e-mail by persons or entities other than the addressee is prohibited. If you have received this e-mail in error, please contact the sender immediately and delete the material from any computer.
von Jeff Steele - 04:57 - 23 Sept. 2026
-
-
Sales and Use Tax Applies to Digital Products Beginning January 1, 2027
Sales and Use Tax Applies to Digital Products Beginning January 1, 2027
Sales and Use Tax Applies to Digital Products Beginning January 1, 2027
Beginning January 1, 2027, the definition of tangible personal property in the Sales and Use Tax Law will be expanded to include digital products and any copyright or patent interests associated with those digital products. As a result, retail sales of digital products in this state or the storage, use, or other consumption in this state of digital products purchased from any retailer may be subject to sales and use tax.
This change is the result of a new law and generally affects:
- Sellers of prewritten computer software
- Prewritten Software-as-a-Service (SaaS) providers
- Businesses that license or provide remote access to prewritten software
- Purchasers of digital products
What is a digital product?
A digital product is prewritten computer software transferred on tangible storage media, transferred electronically, or accessed remotely.
Prewritten computer software is computer software that is held or exists for general or repeated sale or lease, even if it was initially developed on a custom basis or for in-house use, including the combination of two or more prewritten programs.
What items are not digital products?
The following items are not considered digital products under the new law:
- Digital assets (such as cryptocurrency)
- Digital audio works (such as music, spoken recordings, and ringtones)
- Digital audiovisual works (such as movies and videos with sounds)
- Digital books (also known as eBooks)
- Digital infrastructure (such as cloud platforms that allow customers to create, deploy, or run their own software applications)
- Digital video game products
- Digital visual works (such as computer-generated artwork)
What digital products are exempt?
The following digital products are exempt under the new law:
- Digital products representing a service, not including SaaS
- Custom computer software
- Digital products transferred with reproduction and distribution rights
- Digital products purchased solely for use outside of California
Threshold rule that may shift tax liability from retailer to purchaser
When the aggregate gross receipts from sales of digital products by a retailer to a purchaser that are transferred electronically or accessed remotely exceed $5 million in a calendar year or preceding calendar year, the tax liability may shift from the retailer to the purchaser. When this happens, the purchaser may be required to register for a Use Tax Direct Payment Permit and report the tax directly to us. Refer to our Tax Guide for Retailers and Purchasers of Digital Products for more information.
Place of sale and use of digital products
For local and district tax reporting purposes, the place of sale of digital products transferred electronically or accessed remotely is generally the customer’s address, and the place of use is the place where the person accessing the digital product is located. Refer to our Tax Guide for Retailers and Purchasers of Digital Products for more information.
Registration
Digital product sellers in California who are not currently registered with us must register for a seller’s permit, file sales and use tax returns, and report and pay tax on retail sales of digital products.
Out-of-state sellers of digital products engaged in business in this state as defined in Revenue and Taxation Code section 6203 must register with us for a Certificate of Registration—Use Tax, collect and report use tax from retail sales of digital products sold to California consumers, and pay the tax to us.
Our Online Services offers a convenient, fast, and free way to register online for a permit, license, or account.
Legislation information
Senate Bill 122 (Stats. 2026, ch. 23) was signed into law on June 29, 2026.
For more information
Please refer to our Tax Guide for Retailers and Purchasers of Digital Products. You may also call our Customer Service Center at 1‑800‑400‑7115 (TTY:711). Customer service representatives are available Monday through Friday from 7:30 a.m. to 5:00 p.m. (Pacific time), except state holidays.
To be added to our distribution list regarding upcoming interested parties meetings to discuss regulatory issues related to a specific topic, including digital products, or to all topics in general, please send your contact information to PPDD-BTC.InformationRequests@cdtfa.ca.gov.

Thank you for connecting with us.


em-1557
This email was sent to info@turnpack.com
why did I get this? unsubscribe from this list update subscription preferences
CDTFA · 651 Bannon Street · Suite 100, · Sacramento, CA 95811 · USA
von "CDTFA" <noreplynotifications@notifications.cdtfa.ca.gov> - 01:56 - 15 Sept. 2026-
Re: FW: Sales and Use Tax Applies to Digital Products Beginning January 1, 2027
We only sell this: Custom computer software -> so we should be exempt which brings up a good point on items we have paid tax on before. Let me check a few thingsOn Tue, Sep 15, 2026 at 11:18 AM Turnpack LLC <info@turnpack.com> wrote:Do we sell this?
This change is the result of a new law and generally affects:
· Sellers of prewritten computer software
· Prewritten Software-as-a-Service (SaaS) providers
· Businesses that license or provide remote access to prewritten software
· Purchasers of digital products
Thank you for your time,
Lorena Carrillo
From: CDTFA <noreplynotifications@notifications.cdtfa.ca.gov>
Sent: Tuesday, September 15, 2026 10:56 AM
To: info@turnpack.com
Subject: Sales and Use Tax Applies to Digital Products Beginning January 1, 2027Sales and Use Tax Applies to Digital Products Beginning January 1, 2027
Beginning January 1, 2027, the definition of tangible personal property in the Sales and Use Tax Law will be expanded to include digital products and any copyright or patent interests associated with those digital products. As a result, retail sales of digital products in this state or the storage, use, or other consumption in this state of digital products purchased from any retailer may be subject to sales and use tax.
This change is the result of a new law and generally affects:
· Sellers of prewritten computer software
· Prewritten Software-as-a-Service (SaaS) providers
· Businesses that license or provide remote access to prewritten software
· Purchasers of digital products
What is a digital product?
A digital product is prewritten computer software transferred on tangible storage media, transferred electronically, or accessed remotely.
Prewritten computer software is computer software that is held or exists for general or repeated sale or lease, even if it was initially developed on a custom basis or for in-house use, including the combination of two or more prewritten programs.
What items are not digital products?
The following items are not considered digital products under the new law:
· Digital assets (such as cryptocurrency)
· Digital audio works (such as music, spoken recordings, and ringtones)
· Digital audiovisual works (such as movies and videos with sounds)
· Digital books (also known as eBooks)
· Digital infrastructure (such as cloud platforms that allow customers to create, deploy, or run their own software applications)
· Digital video game products
· Digital visual works (such as computer-generated artwork)
What digital products are exempt?
The following digital products are exempt under the new law:
· Digital products representing a service, not including SaaS
· Custom computer software
· Digital products transferred with reproduction and distribution rights
· Digital products purchased solely for use outside of California
Threshold rule that may shift tax liability from retailer to purchaser
When the aggregate gross receipts from sales of digital products by a retailer to a purchaser that are transferred electronically or accessed remotely exceed $5 million in a calendar year or preceding calendar year, the tax liability may shift from the retailer to the purchaser. When this happens, the purchaser may be required to register for a Use Tax Direct Payment Permit and report the tax directly to us. Refer to our Tax Guide for Retailers and Purchasers of Digital Products for more information.
Place of sale and use of digital products
For local and district tax reporting purposes, the place of sale of digital products transferred electronically or accessed remotely is generally the customer’s address, and the place of use is the place where the person accessing the digital product is located. Refer to our Tax Guide for Retailers and Purchasers of Digital Products for more information.
Registration
Digital product sellers in California who are not currently registered with us must register for a seller’s permit, file sales and use tax returns, and report and pay tax on retail sales of digital products.
Out-of-state sellers of digital products engaged in business in this state as defined in Revenue and Taxation Code section 6203 must register with us for a Certificate of Registration—Use Tax, collect and report use tax from retail sales of digital products sold to California consumers, and pay the tax to us.
Our Online Services offers a convenient, fast, and free way to register online for a permit, license, or account.
Legislation information
Senate Bill 122 (Stats. 2026, ch. 23) was signed into law on June 29, 2026.
For more information
Please refer to our Tax Guide for Retailers and Purchasers of Digital Products. You may also call our Customer Service Center at 1‑800‑400‑7115 (TTY:711). Customer service representatives are available Monday through Friday from 7:30 a.m. to 5:00 p.m. (Pacific time), except state holidays.
To be added to our distribution list regarding upcoming interested parties meetings to discuss regulatory issues related to a specific topic, including digital products, or to all topics in general, please send your contact information to PPDD-BTC.InformationRequests@cdtfa.ca.gov.
Thank you for connecting with us.
em-1557
--Christopher Berger
von Chris Berger - 02:22 - 15 Sept. 2026-
Re: FW: Sales and Use Tax Applies to Digital Products Beginning January 1, 2027
Yes that's what I meant. We have sold Software products in CA before but they'd be under Custom Software so there should have been no tax on it. I will checkOn Tue, Sep 15, 2026 at 11:25 AM Info @ Turnpack <info@turnpack.com> wrote:This is for us to start taxing CA sales. NOT what we buy.Lorena Carrillo
Office Manager
Office: 480-331-1878
Direct Line: 781-938-0069
NEW ADDRESS: 6922 Via Northgate Ste 101, Mesa, AZ 85212
lcarrillo@turnpack.com | www.turnpack.com
https://www.turnpack.com/midas-rework/delidderOn Tue, Sep 15, 2026, 11:21 AM Christopher Berger <cberger@turnpack.com> wrote:We only sell this: Custom computer software -> so we should be exempt which brings up a good point on items we have paid tax on before. Let me check a few thingsOn Tue, Sep 15, 2026 at 11:18 AM Turnpack LLC <info@turnpack.com> wrote:Do we sell this?
This change is the result of a new law and generally affects:
· Sellers of prewritten computer software
· Prewritten Software-as-a-Service (SaaS) providers
· Businesses that license or provide remote access to prewritten software
· Purchasers of digital products
Thank you for your time,
Lorena Carrillo
From: CDTFA <noreplynotifications@notifications.cdtfa.ca.gov>
Sent: Tuesday, September 15, 2026 10:56 AM
To: info@turnpack.com
Subject: Sales and Use Tax Applies to Digital Products Beginning January 1, 2027Sales and Use Tax Applies to Digital Products Beginning January 1, 2027
Beginning January 1, 2027, the definition of tangible personal property in the Sales and Use Tax Law will be expanded to include digital products and any copyright or patent interests associated with those digital products. As a result, retail sales of digital products in this state or the storage, use, or other consumption in this state of digital products purchased from any retailer may be subject to sales and use tax.
This change is the result of a new law and generally affects:
· Sellers of prewritten computer software
· Prewritten Software-as-a-Service (SaaS) providers
· Businesses that license or provide remote access to prewritten software
· Purchasers of digital products
What is a digital product?
A digital product is prewritten computer software transferred on tangible storage media, transferred electronically, or accessed remotely.
Prewritten computer software is computer software that is held or exists for general or repeated sale or lease, even if it was initially developed on a custom basis or for in-house use, including the combination of two or more prewritten programs.
What items are not digital products?
The following items are not considered digital products under the new law:
· Digital assets (such as cryptocurrency)
· Digital audio works (such as music, spoken recordings, and ringtones)
· Digital audiovisual works (such as movies and videos with sounds)
· Digital books (also known as eBooks)
· Digital infrastructure (such as cloud platforms that allow customers to create, deploy, or run their own software applications)
· Digital video game products
· Digital visual works (such as computer-generated artwork)
What digital products are exempt?
The following digital products are exempt under the new law:
· Digital products representing a service, not including SaaS
· Custom computer software
· Digital products transferred with reproduction and distribution rights
· Digital products purchased solely for use outside of California
Threshold rule that may shift tax liability from retailer to purchaser
When the aggregate gross receipts from sales of digital products by a retailer to a purchaser that are transferred electronically or accessed remotely exceed $5 million in a calendar year or preceding calendar year, the tax liability may shift from the retailer to the purchaser. When this happens, the purchaser may be required to register for a Use Tax Direct Payment Permit and report the tax directly to us. Refer to our Tax Guide for Retailers and Purchasers of Digital Products for more information.
Place of sale and use of digital products
For local and district tax reporting purposes, the place of sale of digital products transferred electronically or accessed remotely is generally the customer’s address, and the place of use is the place where the person accessing the digital product is located. Refer to our Tax Guide for Retailers and Purchasers of Digital Products for more information.
Registration
Digital product sellers in California who are not currently registered with us must register for a seller’s permit, file sales and use tax returns, and report and pay tax on retail sales of digital products.
Out-of-state sellers of digital products engaged in business in this state as defined in Revenue and Taxation Code section 6203 must register with us for a Certificate of Registration—Use Tax, collect and report use tax from retail sales of digital products sold to California consumers, and pay the tax to us.
Our Online Services offers a convenient, fast, and free way to register online for a permit, license, or account.
Legislation information
Senate Bill 122 (Stats. 2026, ch. 23) was signed into law on June 29, 2026.
For more information
Please refer to our Tax Guide for Retailers and Purchasers of Digital Products. You may also call our Customer Service Center at 1‑800‑400‑7115 (TTY:711). Customer service representatives are available Monday through Friday from 7:30 a.m. to 5:00 p.m. (Pacific time), except state holidays.
To be added to our distribution list regarding upcoming interested parties meetings to discuss regulatory issues related to a specific topic, including digital products, or to all topics in general, please send your contact information to PPDD-BTC.InformationRequests@cdtfa.ca.gov.
Thank you for connecting with us.
em-1557
--Christopher Berger--Christopher Berger
von Chris Berger - 02:41 - 15 Sept. 2026
-
-
Fwd: Your Path To Partnership.
Can you sign us up for a SW Business account?---------- Forwarded message ---------
From: Southwest Business SDR <southwestbusiness@wnco.com>
Date: Tue, Sep 15, 2026 at 8:05 AM
Subject: Your Path To Partnership.
To: <cberger@turnpack.com>Hi Christopher,
You can get started today by getting your CID here. Make sure you have your company's EIN (Employer Identification Number; also known as Federal Tax Identification Number) available when you enroll.
Thank you again for your interest in Southwest® Business! Your next step is to get your Company Identification (CID) number and gain access to all our great benefits.
Get your Company Identification (CID) number
Having a CID number opens the door to everything a partnership with Southwest Business has to offer. When you get your CID, you’ll have access to our free self-service corporate booking tool SWABIZ®, as well as the ability to book through our other business channels, including GDS and Direct Connect/API.
Explore potential benefits
Your organization may be eligible to enjoy exclusive promotions and travel incentives to help your travel budget go further.
Eligible organizations can access online reporting tools including duty of care, travel spend tracking, and unused funds.
Travelers can continue to earn Rapid Rewards points from our award-winning Rapid Rewards program.1
Apply for our business loyalty program, Rapid Rewards Business, which allows eligible companies to earn Rapid Rewards Business points for Southwest travel booked under their CID in SWABIZ®, Direct Connect/API, or GDS. 2
Thank you,
Southwest Business SDR
1All Rapid Rewards® rules and regulations apply and can be found at Southwest.com/rrterms.
2All Rapid Rewards Business rules and regulations apply and can be found at business.southwest.com/Terms-and-Conditions.
Click here to set your email preferences.--Christopher Berger
von Chris Berger - 11:32 - 15 Sept. 2026-
Re: Your Path To Partnership.
Thank you. I will try it out on my next flightOn Tue, Sep 15, 2026 at 10:27 AM Turnpack LLC <info@turnpack.com> wrote:There website is wonky SWABIZ 90451001
Thank you for your time,
Lorena Carrillo
From: Christopher Berger <cberger@turnpack.com>
Sent: Tuesday, September 15, 2026 8:30 AM
To: Info at Turnpack <info@turnpack.com>
Subject: Fwd: Your Path To Partnership.Can you sign us up for a SW Business account?
---------- Forwarded message ---------
From: Southwest Business SDR <southwestbusiness@wnco.com>
Date: Tue, Sep 15, 2026 at 8:05 AM
Subject: Your Path To Partnership.
To: <cberger@turnpack.com>Hi Christopher,
Thank you again for your interest in Southwest® Business! Your next step is to get your Company Identification (CID) number and gain access to all our great benefits.
Get your Company Identification (CID) number
Having a CID number opens the door to everything a partnership with Southwest Business has to offer. When you get your CID, you’ll have access to our free self-service corporate booking tool SWABIZ®, as well as the ability to book through our other business channels, including GDS and Direct Connect/API.
Explore potential benefits
Your organization may be eligible to enjoy exclusive promotions and travel incentives to help your travel budget go further.
Eligible organizations can access online reporting tools including duty of care, travel spend tracking, and unused funds.
Travelers can continue to earn Rapid Rewards points from our award-winning Rapid Rewards program.1
Apply for our business loyalty program, Rapid Rewards Business, which allows eligible companies to earn Rapid Rewards Business points for Southwest travel booked under their CID in SWABIZ®, Direct Connect/API, or GDS. 2You can get started today by getting your CID here. Make sure you have your company's EIN (Employer Identification Number; also known as Federal Tax Identification Number) available when you enroll.
Thank you,
Southwest Business SDR1All Rapid Rewards® rules and regulations apply and can be found at Southwest.com/rrterms.
2All Rapid Rewards Business rules and regulations apply and can be found at business.southwest.com/Terms-and-Conditions.
Click here to set your email preferences.--
Christopher Berger
Phone: +1 (480) 331-1878
Cell: +1 (480) 273-4686
cberger@turnpack.com | www.turnpack.com
--Christopher Berger
von Chris Berger - 01:51 - 15 Sept. 2026
-
-
RE: AAID 18820571 76 WEG AX9Y65 05/17/2025-05/17/2026 DISPUTE (Encrypted Delivery)
Hello Lorena,
Thank you for your correspondence. I've referred your dispute documents to the auditor for review. Please note that revisions take approximately 30 days; therefore, I have placed the initial audit on hold until the revision is completed.
If you have any questions, please let us know.Sincerely,
Zachary Warchal
Audit Service Coordinator & Tier 2 Billing
AuditThe Hartford
301 Woods Park Dr. (NHBC / 2nd Floor)
Clinton, NY 13323
Office (866) 467-8730(Insured) - (877)853-2582- (Agent)
Fax (866)868-6153
Email: esc.audit@thehartford.com
We care about meeting your service expectations. Did I provide you with a great Hartford Experience? Please feel free to send any feedback on my service to Thomas.Mashia@thehartford.com
Business Insurance | Employee Benefits | Personal Insurance
From: info@turnpack.com <info@turnpack.com>
Sent: Monday, September 14, 2026 4:51 PM
To: Esc.Audit@thehartford.com
Cc: cberger@turnpack.com
Subject: AAID 18820571 76 WEG AX9Y65 05/17/2025-05/17/2026 DISPUTEThank you for the information. Please see attached disputes for each company added to our worker comp and business owners policies. Please let me know if any additional information is requested. We only have 1 location and do faithfully believe
ZjQcmQRYFpfptBannerStart
CAUTION: This email originated from outside the organization. Do not click links or open attachments unless you recognize the sender and know the content is safe.
ZjQcmQRYFpfptBannerEnd
Thank you for the information. Please see attached disputes for each company added to our worker comp and business owners policies.
Please let me know if any additional information is requested.
We only have 1 location and do faithfully believe these companies and their our of state addresses were wrongfully added to our accounts.
Lorena Carrillo
Office Manager
Office: 480-331-1878
Direct Line: 781-938-0069
NEW ADDRESS: 6922 Via Northgate Ste 101, Mesa, AZ 85212lcarrillo@turnpack.com | www.turnpack.com
https://www.turnpack.com/midas-rework/delidderFrom: Audit, Esc (PremAudit, New Hartford/Center) <Esc.Audit@thehartford.com>
Sent: Friday, August 21, 2026 10:08 AM
To: info@turnpack.com
Subject: AAID 18820571 76 WEG AX9Y65 05/17/2025-05/17/2026 (Encrypted Delivery)Hi Christopher,
Thank you for contacting The Hartford.
Please provide a written dispute including the following:
- Policy number and the term being disputed
- Contact information for the person disputing the audit including name, phone number and email address
- Amount paid to each subcontractor in dispute
- Please provide workers compensation certificates of insurance for the subcontractors, showing coverage effective during the audit period
If workers compensation certificates cannot be provided, please answer the following questions for each subcontractor:
- Does the contractor have their own employees or helpers?
- Does the insured supervise work/performance, or provide instructions on how work is done?
- Is the work similar to work performed by the insured’s employees?
- Is the work an integral part of the insured’s services or products?
- Does the insured own/lease the work location or set mandatory hours?
- Does the insured provide materials, tools, equipment, or reimburse expenses?
- Is the worker paid hourly, salary, or per day (instead of by job)?
- Is the person used daily or on another frequent ongoing basis?
- Does the insured provide benefits (vacation, sick time, bonuses, insurance)?
- Is this specialty work commonly performed on a contract basis?
- Does the person operate as a legal entity AND advertise as a business?
- Does the contractor have to perform the work personally (cannot subcontract)?
The required correspondence can be sent via fax (888-841-5831) or email esc.audit@thehartford.com.
If you have any questions or need assistance, one of our Hartford Premium Audit representatives will be happy to assist you. Please contact us:
By phone: 800-447-7649 Monday – Friday 8 a.m. to 8 p.m. EST
By email: esc.audit@thehartford.com
Thank you and have a great day
…………
Keyana Randall
Audit Service Coordinator
The Hartford Insurance Group, Inc.
3600 Wiseman Blvd.
San Antonio, TX 78251
Office (866) 467-8730
Mobile (877) 853-2582
Fax (866) 868-6153
Business Insurance | Employee Benefits | Auto | Home
We care about meeting your service expectations. Did I provide you with a great experience? Please feel free to send any feedback on my service to Melissa.Sonia@thehartford.com
******************************************************************************************************
This communication, including attachments, is for the exclusive use of addressee and may contain proprietary, confidential and/or privileged information. If you are not the intended recipient, any use, copying, disclosure, dissemination or distribution is strictly prohibited. If you are not the intended recipient, please notify the sender immediately by return e-mail, delete this communication and destroy all copies.
******************************************************************************************************
******************************************************************************************************
This communication, including attachments, is for the exclusive use of addressee and may contain proprietary, confidential and/or privileged information. If you are not the intended recipient, any use, copying, disclosure, dissemination or distribution is strictly prohibited. If you are not the intended recipient, please notify the sender immediately by return e-mail, delete this communication and destroy all copies.
******************************************************************************************************
von "Audit, Esc (PremAudit, New Hartford/Center)" <Esc.Audit@thehartford.com> - 11:32 - 15 Sept. 2026 -
Confirmed ▪️ NEW Partner Offers
 Savings & More from Top Brands ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏ ͏

View as a web page 


Building Materials Electrical Paint Plumbing Tools Bulk
Building Materials Electrical Paint Plumbing Tools Bulk 


QUICK LINKS Mobile App Pro Local Ad Pro Pick™ Product Videos INFORMATION Privacy & Security Contact Us Store Finder This email was sent to info@turnpack.com.
Except as noted, prices valid through 09/22/2026. Pricing and availability may vary by store.
To unsubscribe from future emails, click here.
For licenses, see homedepot.com/licensenumbers.
NOTE: All offers may not be available in all areas. Prices are in U.S. dollars and are subject to change without notice.
2455 Paces Ferry Road, N.W., Atlanta, GA 30339-4024, USA.
©2026 Home Depot Product Authority, LLC. All rights reserved.
von "Home Depot Pro Xtra" <homedepotpro@mg.homedepot.com> - 11:26 - 15 Sept. 2026 -
Invoice for Your Order PO26371913
InvoiceBilled toTURNPACK LLC
6922 E VIA NORTHGATE STE 101
MESA AZ 85212Purchase Order PO26371913 Total $123.06 Invoice 71849042 Invoice Date 9/14/26 Payment Terms 2% 10, Net 30 Deduct $1.44 on merchandise if paid by 9/24/26. Shipped toTurnpack LLC
6922 E Via Northgate Ste 101
Mesa AZ 85212Mail Payment to McMaster-Carr
PO Box 7690
Chicago IL 60680-7690Your Account 438808000 Christopher Berger placed this order.Line Product Ordered Shipped Balance Price Total 1 8975K11 Multipurpose 6061 Aluminum Bar, 1/2" Thick x 1" Wide, 6 Feet Long 1 Each1 0 39.15 Each39.15 2 2281A1 Metric Class Z Plug Gauge, Tool Steel, Go Gauge, 0.7000 mm Size 1 Each1 0 8.85 Each8.85 3 92125A052 18-8 Stainless Steel Hex-Drive Flat Head Screw, M2 x 0.4 mm Thread Size, 6 mm Long, Packs of 50 2 Packs2 0 12.00 Per Pack24.00 Merchandise 72.00 Shipping 51.06 Total $123.06 Packing List Shipped Weight Carrier Tracking 5557007-01 09/14/2026 12 lb FedEx 541303233226 5557007-02 09/14/2026 1 lb FedEx 541303233237 Federal ID 36-1458720
von "McMaster-Carr" <invoice.reply@mcmaster.com> - 03:22 - 15 Sept. 2026